Sainsbury's (SBRY) is my favourite of the Listed supermarkets, simply because they seem to be executing better than the others. Also, it's intangible, but as a customer when shopping at Sainsbury's, I just somehow feel positive (maybe it's the colour scheme, store layouts, staff attitude, the product, who knows?). When I shop in Tesco, it feels the opposite - somehow more stressful and unpleasant. Can't explain it, but there has to be a reason for that.
With a positive Xmas trading update issued this morning, with LFL sales up 1.5%, it's put SBRY back on my shopping list at 329p, so have picked up a few. The forecast yield is almost 5%, and the PER 11, so those figures look attractive to me. Always the possibility that the Qataris, who own 26% might bid for the whole thing at some point, so I like SBRY as a nice each-way bet.
Fashion group Ted Baker (TED) once again shows how it's done, with an excellent trading update for the 8 weeks to 5 Jan. Retail sales rose 20.9% vs last year, and with sq footage up 13.9%, that means LFL sales are up roughly 7%, a remarkable performance in the current climate.
It just goes to prove what I've always said - if you get the product & the price right, it will sell, regardless of market conditions.
Profits at TED will be in line with expectations. The share price already reflects this strong performance, with a PER of just over 20. It's not for me, as it only takes one season's range to go wrong, and a profits warning, to trigger a 30% plunge in share price. So for me the potential reward does not justify the risk.
But I'll be the guy buying 30% lower if they do warn on profits at any point!
Today's rant has to be about market makers, and their ridiculous spreads again. Take Vianet (VNET), a share which I'm very keen on, as it's the ideal mix of value (fwd PER of 6.7 times next year's fc EPS of 17p, and 5% divi yield, with a sound balance sheet) and good growth potential thrown in for free.
There has been a fair bit of volume lately, typically 100-200k shares traded each day, if not more. So the market spread should be maybe 1-2% right? Wrong! Despite having 5 market makers providing quotes (of just 1,000 shares!), their resting position is a bid/offer spread of 7p. On a share that is just over a quid. Absolutely crazy.
Moreover, they don't compete with each other, they just rush to match each other's stance, leaving the spread so impossibly wide that they have effectively almost shut down the market in VNET shares. Nobody is going to trade if they have to absorb a 7% bid/offer spread, plus dealing costs. Get a grip please market makers! Either quote sensible prices, or don't bother quoting prices at all!
What makes it worse, is that the actual price of trades going through is well within the quoted spread. So why do they insist on quoting prices which are far wider than the actual prices they are prepared to deal at? It just creates hassle, and deters people from dealing. So instead we have to go to an online broker, put in dummy trades, to see what the price on the RSP actually is. A ridiculous waste of time.
My preference would be to have ALL stocks on the market as SETSmm stocks, so that investors can place orders directly on the order book (if you have DMA), or instruct your broker to do so, by-passing the market makers altogether.
This is a serious issue, where the status quo is massively holding back the market in small caps. We need much tighter spreads, and more liquidity (which will flow naturally from tighter spreads). The market makers current strategy of extreme caution is greatly holding back the small caps market in my opinion. Action is needed!
Gregg's (GRG) didn't have a great Xmas, with LFL sales down 2.9% against strong 2011 comparatives. Although they do say full year results to be broadly in line with expectations. PER is 11, and divi yield 4.6%, but growth prospects look limited. So probably priced about right.
High performance foams maker, Zotefoams (ZTF) puts out a positive trading statement, with Q4 sales up 8%, and expectation of 2012 being in line. The valuation looks about right for a steady growth company, with a fwd PER of about 15.
Oh, just a quick plug for an investor London event next week, which I shall be attending. It's a similar format to Dave Stredder's "Mello" investment evenings, in that 3 Listed companies will be giving short presentations, followed by Q&A. Then drinks/canapes & networking afterwards. It's all free, and is being organised by Equity Development, who are sharpening their focus on private investors, hence why they are organising this event.
Should be a good evening, as the 3 companies are excellent growth small caps: Tracsis, Regenersis, and VP Group.
Details are here for anyone interested, as there are still some spaces left;
http://equitydevelopment.co.uk/index.php?p=news
Right, I have to dash, so that's it for today. Back tomorrow.
Regards, Paul.
Wednesday, January 9, 2013

Tuesday, January 8, 2013
Tue 8 Jan - ALL, MJW, DOM, DPP, VNET, STVG, DEB, TPT, DNLM
The year-end trading statements are starting to flow now, with about 16 issued this morning. So I will review 4 or 5 that look the most interesting to me, with a small cap and retailing leaning.
Allocate Software (ALL) has an unusual 31 May year-end, so their H1 trading update this morning relates to the 6m to 30 Nov 2012. They say that H1 is in line with expectations, but split between a slow Q1 and a "much stronger" Q2. The outlook statement is pretty upbeat, so might be worth a closer look? Although with 5.5p EPS forecast for 2012/13, a share price of 78p prices it on a PER of 14.2, which doesn't excite me. As a value investor I'm looking for decent growth and a PER well below 10.
Majestic Wine (MJW) shares have done very well, rising 4-fold in the last 4 years. Their Xmas trading statement is pretty solid - total sales up 5.1%, with like-for-like ("LFL") sales up 1.1% for UK stores.
There is no reference to profit vs expectations, but given that Xmas trading was slightly ahead of the year-to-date (they report 0.8% LFL sales growth for the 39 weeks to 31 Dec), then one assumes they are in line with expectations. But this should have been made clearer from the RNS.
Interestingly, Majestic do note that many shoppers left purchases to the last minute, an increasing worry for shops at Xmas time. This behaviour may be explained by the fact that shops rarely run out of things these days, so by being good at logistics, in a way they've shot themselves in the foot?
Dominos Pizza (DOM) trading updates are always a pleasure to read, and yet again they've delivered good growth, and say that profits are in line with expectations. The shares are certainly not cheap, with a fwd PER over 20, but what a great business.
Interesting also that they flag good overseas growth, particularly in Germany. This might have some read-across to long-suffering shareholders in DP Poland (DPP), the separately Listed franchisee for the new Domino's stores in Poland, which recently completed a fund-raising to continue its expansion.
I was pleased to see the overhang from seller New Solera finally cleared in Vianet (VNET) yesterday, with the stock popping up 15% to 117p. Market makers are doing their best to inhibit trading though, with a ludicrous 5p spread. I wish we could move to a SETS order book on every stock, where anybody can effectively become a market maker, and spreads narrow.
I highlighted the great value (low PER, high divi yield) and strong growth prospects thrown in for free with Vianet shares here on my Small Cap Value website back in Nov, where the stock overhang gave many of us the chance to buy as many shares as we wanted, without moving the price. So I tend to view a stock overhang (where a large holder is gradually liquidating their position in the market) as an opportunity, rather than a problem.
Another of my stocks coming alive in the last few days, is STV Group (STVG), although I haven't seen any news, or reason for the rise. If anyone knows why it is rising strongly, please let us know on the comments section of this post.
I value interesting reader feedback, and do my best to respond to most feedback, if time permits.
Debenhams (DEB) had a very good Xmas by the looks of it - LFL sales up a whopping 5% in the busiest 5 weeks to 5 Jan 2013. Very impressive. I hope that has some read-across for French Connection (FCCN), a potential turnaround share which I hold.
Topps Tiles (TPT) Q1 IMS looks OK, with LFL sales up 1.6% (although that is against soft comparatives of down 4.2% the prior year).
Dunelm (DNLM) has also had a good Xmas, with H1 LFL sales to 29 Dec 2012 up 2.2%, against a 1.1% rise the prior year. Although they do note that strong H2 comparatives will be tough to match.
There are a few more, but that's as many as I can cope with before my first cup of tea of the day! Just a quick word of thanks also to the many generous donations made yesterday to my 2 charitable causes (see box on top right hand side of this page). It is hugely appreciated, and spurred me on to do another 5 mile training run last night after the markets closed. They are definitely getting easier the more often I do them.
Regards, Paul.
(of the shares mentioned today, Paul holds VNET, FCCN, and STVG only).
Allocate Software (ALL) has an unusual 31 May year-end, so their H1 trading update this morning relates to the 6m to 30 Nov 2012. They say that H1 is in line with expectations, but split between a slow Q1 and a "much stronger" Q2. The outlook statement is pretty upbeat, so might be worth a closer look? Although with 5.5p EPS forecast for 2012/13, a share price of 78p prices it on a PER of 14.2, which doesn't excite me. As a value investor I'm looking for decent growth and a PER well below 10.
Majestic Wine (MJW) shares have done very well, rising 4-fold in the last 4 years. Their Xmas trading statement is pretty solid - total sales up 5.1%, with like-for-like ("LFL") sales up 1.1% for UK stores.
(Explanation of "Like-for-like" (LFL) sales - this is a method of reporting sales, used particularly by retailers, which shows the underlying performance of the business. So it strips out any newly opened or closed stores, and only reports on the stores which have been open for the full period both this year, and last year. Therefore the total % LFL change in sales gives the most meaningful figure to judge performance on. So in the example above, Majestic Wine achieved +1.1% LFL sales in their shops which were open both last year and this year. However, total sales for the whole business rose 5.1%. This indicates that they have opened new stores equating to 4% additional sales (so 1.1% LFL + 4% new stores = 5.1% total sales growth).
There is no reference to profit vs expectations, but given that Xmas trading was slightly ahead of the year-to-date (they report 0.8% LFL sales growth for the 39 weeks to 31 Dec), then one assumes they are in line with expectations. But this should have been made clearer from the RNS.
Interestingly, Majestic do note that many shoppers left purchases to the last minute, an increasing worry for shops at Xmas time. This behaviour may be explained by the fact that shops rarely run out of things these days, so by being good at logistics, in a way they've shot themselves in the foot?
Dominos Pizza (DOM) trading updates are always a pleasure to read, and yet again they've delivered good growth, and say that profits are in line with expectations. The shares are certainly not cheap, with a fwd PER over 20, but what a great business.
Interesting also that they flag good overseas growth, particularly in Germany. This might have some read-across to long-suffering shareholders in DP Poland (DPP), the separately Listed franchisee for the new Domino's stores in Poland, which recently completed a fund-raising to continue its expansion.
I was pleased to see the overhang from seller New Solera finally cleared in Vianet (VNET) yesterday, with the stock popping up 15% to 117p. Market makers are doing their best to inhibit trading though, with a ludicrous 5p spread. I wish we could move to a SETS order book on every stock, where anybody can effectively become a market maker, and spreads narrow.
I highlighted the great value (low PER, high divi yield) and strong growth prospects thrown in for free with Vianet shares here on my Small Cap Value website back in Nov, where the stock overhang gave many of us the chance to buy as many shares as we wanted, without moving the price. So I tend to view a stock overhang (where a large holder is gradually liquidating their position in the market) as an opportunity, rather than a problem.
Another of my stocks coming alive in the last few days, is STV Group (STVG), although I haven't seen any news, or reason for the rise. If anyone knows why it is rising strongly, please let us know on the comments section of this post.
I value interesting reader feedback, and do my best to respond to most feedback, if time permits.
Debenhams (DEB) had a very good Xmas by the looks of it - LFL sales up a whopping 5% in the busiest 5 weeks to 5 Jan 2013. Very impressive. I hope that has some read-across for French Connection (FCCN), a potential turnaround share which I hold.
Topps Tiles (TPT) Q1 IMS looks OK, with LFL sales up 1.6% (although that is against soft comparatives of down 4.2% the prior year).
Dunelm (DNLM) has also had a good Xmas, with H1 LFL sales to 29 Dec 2012 up 2.2%, against a 1.1% rise the prior year. Although they do note that strong H2 comparatives will be tough to match.
There are a few more, but that's as many as I can cope with before my first cup of tea of the day! Just a quick word of thanks also to the many generous donations made yesterday to my 2 charitable causes (see box on top right hand side of this page). It is hugely appreciated, and spurred me on to do another 5 mile training run last night after the markets closed. They are definitely getting easier the more often I do them.
Regards, Paul.
(of the shares mentioned today, Paul holds VNET, FCCN, and STVG only).
Monday, January 7, 2013
Mon 7 Jan - STAF, NPT
Good morning! Here is my usual trawl through the morning's RNSs, looking for the undervalued and overlooked.
Recruitment/outsourcing group Staffline (STAF) has issued a short & sweet trading statement, saying that 2012 earnings will be in line with market expectations. They reiterate they are, "well placed to continue to capitalise on a number of strategic opportunities that exist across our business", the biggest one of which is the Govt's welfare to work programme (which could become pretty lucrative for STAF in the next 5 years).
Morningstar shows the broker consensus EPS as 33.6p for 2012, so that puts STAF on a fairly cheap PER of 8.9 times 2012 earnings. There is also a 8.3p forecast divi, giving a yield of 2.8%. So it's no longer amazing value, but certainly good value. However, if EPS grows as forecast to 40p (with a 9.5p divi) then the 2013 forecast PER falls to 7.5, and the yield rises to 3.2%, which is looking a lot more interesting.
STAF has been heavily tipped by the Mail on Sunday, so I suspect that pulled in a lot of the recent buyers, so personally I shall sit this one out, and look to buy back in any significant pullback to say the 260-270p area.
On 4 Sep 2012 I published a report here following a private client broker lunch I attended with Staffline's Directors, and was very impressed. I bought shares at 226p, although have recently sold them at c.300p, in order to recycle the money into something that hasn't yet moved up (Vianet), but looks like it will once the overhang from a large seller is cleared.
Incidentally, I also made Staffline the "share of the month" for Sep 2012 on my sister site, Small Cap Value, which I'm pleased to say is now up & running again after some major IT problems (had to recreate the website from scratch, but have installed proper automatic backups now, so should be fine in future).
Netplay TV (NPT), the interactive gaming company, puts out a strong Q4 & full year trading statement, indicating that they are confident of exceeding full year market expectations. So that means they should deliver over 1p EPS for 2012, therefore these look potentially good value at 12.2p.
They note that mobile/tablet is a strong area of growth (isn't it everywhere?!).
I'm not terribly keen on gaming companies, as they are essentially preying on people with addictive personalities, so it's not for me. But purely based on the numbers it looks like a potentially interesting growth company.
OK, that's it for today. Not much else to report, other than that my training runs for the Brighton Half Marathon on 17 Feb are going well - am going out 3 or 4 times per week now, and managed about 5 miles last night with relative ease. Thank you to everyone who has sponsored me for either MacMillan cancer care, or the Sussex Beacon charities. The Justgiving link is here if you wish to donate. I'm at 59% of target funds raised so far ...
Also, I'm doing the DryAthlon for Cancer Research, which is to renounce alcohol for the whole of January. People who know me acknowledge that I (harrumph, coughs!) enjoy a drink occasionally, but so far so good. If you fancy sending me a virtual diet coke (for the benefit of Cancer Research), then please click on this different Justgiving link. Thank you to "Ajay" who kindly donated £20, much appreciated!
Have a good week!
Regards, Paul.
Recruitment/outsourcing group Staffline (STAF) has issued a short & sweet trading statement, saying that 2012 earnings will be in line with market expectations. They reiterate they are, "well placed to continue to capitalise on a number of strategic opportunities that exist across our business", the biggest one of which is the Govt's welfare to work programme (which could become pretty lucrative for STAF in the next 5 years).
Morningstar shows the broker consensus EPS as 33.6p for 2012, so that puts STAF on a fairly cheap PER of 8.9 times 2012 earnings. There is also a 8.3p forecast divi, giving a yield of 2.8%. So it's no longer amazing value, but certainly good value. However, if EPS grows as forecast to 40p (with a 9.5p divi) then the 2013 forecast PER falls to 7.5, and the yield rises to 3.2%, which is looking a lot more interesting.
STAF has been heavily tipped by the Mail on Sunday, so I suspect that pulled in a lot of the recent buyers, so personally I shall sit this one out, and look to buy back in any significant pullback to say the 260-270p area.
On 4 Sep 2012 I published a report here following a private client broker lunch I attended with Staffline's Directors, and was very impressed. I bought shares at 226p, although have recently sold them at c.300p, in order to recycle the money into something that hasn't yet moved up (Vianet), but looks like it will once the overhang from a large seller is cleared.
Incidentally, I also made Staffline the "share of the month" for Sep 2012 on my sister site, Small Cap Value, which I'm pleased to say is now up & running again after some major IT problems (had to recreate the website from scratch, but have installed proper automatic backups now, so should be fine in future).
Netplay TV (NPT), the interactive gaming company, puts out a strong Q4 & full year trading statement, indicating that they are confident of exceeding full year market expectations. So that means they should deliver over 1p EPS for 2012, therefore these look potentially good value at 12.2p.
They note that mobile/tablet is a strong area of growth (isn't it everywhere?!).
I'm not terribly keen on gaming companies, as they are essentially preying on people with addictive personalities, so it's not for me. But purely based on the numbers it looks like a potentially interesting growth company.
OK, that's it for today. Not much else to report, other than that my training runs for the Brighton Half Marathon on 17 Feb are going well - am going out 3 or 4 times per week now, and managed about 5 miles last night with relative ease. Thank you to everyone who has sponsored me for either MacMillan cancer care, or the Sussex Beacon charities. The Justgiving link is here if you wish to donate. I'm at 59% of target funds raised so far ...
Also, I'm doing the DryAthlon for Cancer Research, which is to renounce alcohol for the whole of January. People who know me acknowledge that I (harrumph, coughs!) enjoy a drink occasionally, but so far so good. If you fancy sending me a virtual diet coke (for the benefit of Cancer Research), then please click on this different Justgiving link. Thank you to "Ajay" who kindly donated £20, much appreciated!
Have a good week!
Regards, Paul.
Friday, January 4, 2013
Fri 4 Jan - COST, JSG, CKN, MMC
Another quiet day for RNSs. Engineering group Costain (COST) issues a good solid pre-close trading statement (since their results are due to be issued on 6 March, then the Close Period starts 2 months before that, so 6 Jan).
They finished the year in line with expectations, order book slightly down on last year £2.4bn vs £2.5bn, and with over £700m of work secured for 2013 (presumably up from the "in excess of £650m secured for 2012" at this time last year, although the wording could be ambiguous, since both are in excess of a stated number).
They also have a "strong cash position and no significant borrowings".
This looks a nice steady company, churning out reliable EPS of around 30p on average each year, and a steadily rising divi (10p last year). So the expected EPS of 30p this year puts them on a PER of 8.3, and a divi yield of 4.2%.
At first glance that looks fairly attractive to me, for a company which should benefit from the cyclical upturn in the economy which will happen at some point. So could be worth a further look?
Dry cleaning outfit Johnson Service (JSG) puts out an in line trading statement for y/e 31 Dec. Results will be issued in early March. Interestingly, they say that the dry cleaning estate has shown LFL sales growth, "the first such increase for a number of years".
If dry cleaning is a proxy for the overall health of the economy, then this could be a reassuring sign. Although a trend I have noticed, is that with many people feeling insecure about their jobs, people are tending to dress more smartly in the office, in order to project a more professional image. When I turn up for meetings without a tie these days, I'm usually the only person in the room tie-less. Whereas a couple of years ago there were more open-necked shirts.
So perhaps JSG are benefiting from a trend towards smarter office dress?
Anyway, the shares look fully priced to me, EPS forecast of 4.4p means they are on a PER of about 8.5 at 38p. Cheap? Not really, when you consider they have £59m of debt (which is 62% of their market cap of £95m). So that would take the PER up to almost 14 if you add back the debt. There are better bargains out there in my view.
Shipping broker Clarkson (CKN) issues a brief statement saying that despite challenging markets, trading continues to be in line with expectations. Nice company, but the shares look fairly priced to me (whereas I'm looking for bargains!)
Management Consulting Group (MMC) issues an in line trading statement, and a share repurchase programme. It looks fairly cheap on a PER basis, with 2.7p EPS expected for 2012, so at 23p a share I make that a PER of 8.5.
However, I don't like the balance sheet - loads of intangibles, and too much debt. They note that y/e net debt is £30m, and has reduced well in the last few years. There is a reasonable divi yield of about 3.5%. It's not for me, due to the balance sheet being too weak for my preference.
OK that's it for this week, should be busy next week with lots of trading statements I would imagine, so be sure to check back here every day.
I always Tweet to announce when articles are published here, so if you follow me on Twitter, @paulypilot then you will be amongst the first to know when reports are published (which saves checking back multiple times).
Oh, also want to mention that there is an interesting "meet the management" event being organised by Equity Development on 17 Jan in London, in the evening. The 3 companies presenting all look interesting; Regenersis, Tracsis, and VP Group.
I'm told there are a few spaces left, so if you would like to attend then check out the contact details here.
I shall be attending, so say hello if you also attend! I'll be the guy with no tie!
Regards, Paul.
They finished the year in line with expectations, order book slightly down on last year £2.4bn vs £2.5bn, and with over £700m of work secured for 2013 (presumably up from the "in excess of £650m secured for 2012" at this time last year, although the wording could be ambiguous, since both are in excess of a stated number).
They also have a "strong cash position and no significant borrowings".
This looks a nice steady company, churning out reliable EPS of around 30p on average each year, and a steadily rising divi (10p last year). So the expected EPS of 30p this year puts them on a PER of 8.3, and a divi yield of 4.2%.
At first glance that looks fairly attractive to me, for a company which should benefit from the cyclical upturn in the economy which will happen at some point. So could be worth a further look?
Dry cleaning outfit Johnson Service (JSG) puts out an in line trading statement for y/e 31 Dec. Results will be issued in early March. Interestingly, they say that the dry cleaning estate has shown LFL sales growth, "the first such increase for a number of years".
If dry cleaning is a proxy for the overall health of the economy, then this could be a reassuring sign. Although a trend I have noticed, is that with many people feeling insecure about their jobs, people are tending to dress more smartly in the office, in order to project a more professional image. When I turn up for meetings without a tie these days, I'm usually the only person in the room tie-less. Whereas a couple of years ago there were more open-necked shirts.
So perhaps JSG are benefiting from a trend towards smarter office dress?
Anyway, the shares look fully priced to me, EPS forecast of 4.4p means they are on a PER of about 8.5 at 38p. Cheap? Not really, when you consider they have £59m of debt (which is 62% of their market cap of £95m). So that would take the PER up to almost 14 if you add back the debt. There are better bargains out there in my view.
Shipping broker Clarkson (CKN) issues a brief statement saying that despite challenging markets, trading continues to be in line with expectations. Nice company, but the shares look fairly priced to me (whereas I'm looking for bargains!)
Management Consulting Group (MMC) issues an in line trading statement, and a share repurchase programme. It looks fairly cheap on a PER basis, with 2.7p EPS expected for 2012, so at 23p a share I make that a PER of 8.5.
However, I don't like the balance sheet - loads of intangibles, and too much debt. They note that y/e net debt is £30m, and has reduced well in the last few years. There is a reasonable divi yield of about 3.5%. It's not for me, due to the balance sheet being too weak for my preference.
OK that's it for this week, should be busy next week with lots of trading statements I would imagine, so be sure to check back here every day.
I always Tweet to announce when articles are published here, so if you follow me on Twitter, @paulypilot then you will be amongst the first to know when reports are published (which saves checking back multiple times).
Oh, also want to mention that there is an interesting "meet the management" event being organised by Equity Development on 17 Jan in London, in the evening. The 3 companies presenting all look interesting; Regenersis, Tracsis, and VP Group.
I'm told there are a few spaces left, so if you would like to attend then check out the contact details here.
I shall be attending, so say hello if you also attend! I'll be the guy with no tie!
Regards, Paul.
Thursday, January 3, 2013
Thu 3 Jan - NXT, TED, DLC, SNCL
Interesting RNSs are starting to appear again at long last, and should build into a tidal wave of trading statements over the next couple of weeks, especially from retailers (which I take a particular interest in, as I spent 8 years as the FD for a ladieswear chain).
Fashion bellwether, Next (NXT) is the first fashion retailer to report. I so admire this business, both as an analyst, and as a customer. They just execute consistently well, at everything. Even their trading statements are a model of clarity, giving precise profit & EPS guidance (if they do it, why can't everyone? I often hear company management say, "we can't give forecasts, that's your job", at analyst meetings. My answer from now on will be, "well, Next give precise forecasts to the market, so why can't you?!"). We're only talking about current year forecasts here of course, not future years.
There are no surprises within the Next figures, just slight out-performance against previous guidance, and the trend of Next Directory growing strongly has continued, with sales growth year to date of 10.5%, versus only 0.6% sales growth in Next retail.
They see the outlook as "subdued but steady". Interestingly, Next buys back a hefty chunk of its own shares each year, so a hidden benefit in that EPS has risen in spectacular fashion over the years. It's a clever strategy that has helped drive a remarkable share price performance. As usual, I can't bring myself to buy the shares now that they have already risen so much. The fwd PER is 13.5, which looks about right.
Ted Baker (TED) announce that their trading statement will be issued next week, on Wed 9 Jan.
CAD/CAM software company, Delcam (DLC) puts out a strong trading update, indicating that they finished the year with record orders, saying that they have, "ended an already strong year on a new high". Impressive stuff!
It's always pleasing to see a British company succeeding out there on an international level. The shares have reacted positively, as you would expect, and have punched through 1000p. The PER is getting close to 20, so it's a bit warm for me, but I can see the attraction for growth investors who believe that the growth will continue.
Trouble is with toppy ratings, you're only ever one profit warning away from losing your shirt, which makes it difficult to sleep at night. Personally I'd rather look at fundamentally good companies which have had a temporary slip-up, and are priced for failure, but go on to recover. But each to their own!
Horticultural products group, William Sinclair (SNCL) had a lousy year in 2012, due to the exceptionally wet weather, which hampered harvesting of peat. This more or less wiped out profits for the year, which fell over 90% to just £261k. It's got debt, and a significant pension fund deficit of £13m (compared with £20m mkt cap), and isn't particularly cheap on a PER basis, even if you look at a more normal prior year's trading, so I won't be following up on this one. Too messy.
On a final point, I'm doing another little thing for charity, this time it's Cancer Research's "DryAthlon". The idea is that you don't drink any alcohol for the whole of January, and instead you donate the money you save to Cancer Research. What a great idea! And you can get people to sponsor you too. It is still open for new joiners, so if you fancy having a dry January & helping charity at the same time, then why not sign up?!
I've already tapped my friends here for sponsorship to my Half Marathon on Feb 17th, so am not expecting any more donations to the DryAthlon, but if anyone does feel like giving me a bit of encouragement for a dry January, then my Cancer Research fund-raising page for DryAthlon is here. Why not donate a virtual pint (of diet coke!)?!
Incidentally, my training runs were going very well, got up to 10 miles just before Xmas (although the last 3 miles of that were hobbling/walking/spurts of jogging), but the effects of Xmas food & booze, and a Cold, mean that there's still a lot of work to do. But I went back outside yesterday evening, and managed 4 miles, so am getting back into my stride. Will keep you updated.
A dodgy right ankle is the main problem, rather than stamina (I badly sprained my ankle in April 2012, and it's not fully recovered unfortunately, so seizes up when I run on it). But we'll get there, where there's a will, there's a way!
We're back to daily reports here now, so do check back here every trading day from now on, should be a very busy month for trading statements, then we'll start to get into the mega-busy period of Feb-Mar for 31 Dec year-ends.
Regards, Paul.
(Paul does NOT hold shares in any of the companies mentioned today)
Fashion bellwether, Next (NXT) is the first fashion retailer to report. I so admire this business, both as an analyst, and as a customer. They just execute consistently well, at everything. Even their trading statements are a model of clarity, giving precise profit & EPS guidance (if they do it, why can't everyone? I often hear company management say, "we can't give forecasts, that's your job", at analyst meetings. My answer from now on will be, "well, Next give precise forecasts to the market, so why can't you?!"). We're only talking about current year forecasts here of course, not future years.
There are no surprises within the Next figures, just slight out-performance against previous guidance, and the trend of Next Directory growing strongly has continued, with sales growth year to date of 10.5%, versus only 0.6% sales growth in Next retail.
They see the outlook as "subdued but steady". Interestingly, Next buys back a hefty chunk of its own shares each year, so a hidden benefit in that EPS has risen in spectacular fashion over the years. It's a clever strategy that has helped drive a remarkable share price performance. As usual, I can't bring myself to buy the shares now that they have already risen so much. The fwd PER is 13.5, which looks about right.
Ted Baker (TED) announce that their trading statement will be issued next week, on Wed 9 Jan.
CAD/CAM software company, Delcam (DLC) puts out a strong trading update, indicating that they finished the year with record orders, saying that they have, "ended an already strong year on a new high". Impressive stuff!
It's always pleasing to see a British company succeeding out there on an international level. The shares have reacted positively, as you would expect, and have punched through 1000p. The PER is getting close to 20, so it's a bit warm for me, but I can see the attraction for growth investors who believe that the growth will continue.
Trouble is with toppy ratings, you're only ever one profit warning away from losing your shirt, which makes it difficult to sleep at night. Personally I'd rather look at fundamentally good companies which have had a temporary slip-up, and are priced for failure, but go on to recover. But each to their own!
Horticultural products group, William Sinclair (SNCL) had a lousy year in 2012, due to the exceptionally wet weather, which hampered harvesting of peat. This more or less wiped out profits for the year, which fell over 90% to just £261k. It's got debt, and a significant pension fund deficit of £13m (compared with £20m mkt cap), and isn't particularly cheap on a PER basis, even if you look at a more normal prior year's trading, so I won't be following up on this one. Too messy.
On a final point, I'm doing another little thing for charity, this time it's Cancer Research's "DryAthlon". The idea is that you don't drink any alcohol for the whole of January, and instead you donate the money you save to Cancer Research. What a great idea! And you can get people to sponsor you too. It is still open for new joiners, so if you fancy having a dry January & helping charity at the same time, then why not sign up?!
I've already tapped my friends here for sponsorship to my Half Marathon on Feb 17th, so am not expecting any more donations to the DryAthlon, but if anyone does feel like giving me a bit of encouragement for a dry January, then my Cancer Research fund-raising page for DryAthlon is here. Why not donate a virtual pint (of diet coke!)?!
Incidentally, my training runs were going very well, got up to 10 miles just before Xmas (although the last 3 miles of that were hobbling/walking/spurts of jogging), but the effects of Xmas food & booze, and a Cold, mean that there's still a lot of work to do. But I went back outside yesterday evening, and managed 4 miles, so am getting back into my stride. Will keep you updated.
A dodgy right ankle is the main problem, rather than stamina (I badly sprained my ankle in April 2012, and it's not fully recovered unfortunately, so seizes up when I run on it). But we'll get there, where there's a will, there's a way!
We're back to daily reports here now, so do check back here every trading day from now on, should be a very busy month for trading statements, then we'll start to get into the mega-busy period of Feb-Mar for 31 Dec year-ends.
Regards, Paul.
(Paul does NOT hold shares in any of the companies mentioned today)
Saturday, December 29, 2012
2012 Year-End Review
Well that's almost it for 2012, apart from a half day's trading on Monday 31st December, so I thought this would be a good time to review the share selections from my Blog, in its first year.
Little did I know, when starting this Blog in June 2012 that it would prove popular - with over 151,000 pageviews to date! On average there are around 1,200 readers per day, which is growing steadily.
Whilst that's good, and enough to make it worthwhile me writing here, surely that must only be the tip of the iceberg of people interested in small caps? So hopefully word will spread in 2013 a bit wider? I make a tiny income (£50-100 a month) from the Google ads, so thank you to people who have taken an interest.
I suspect that a lot of private investors/traders focus on the resources sector (which I don't cover at all here), since there have been rich rewards in that sector for quite a few years now, although that seemed to flip around in 2012, with conventional smaller caps generating an excellent year - e.g. the FTSE Small Caps Index is up a whopping 24.3% in 2012.
Therefore, whilst many small cap investors think that they have out-performed the market in 2012, actually most haven't, because they have erroneously compared their performance with the FTSE 100, or the AIM Index (which has been weighed down by under-performing resource sector shares).
So a big thank you to everyone who has taken an interest in my Blog this year, and also a hat tip to my overseas readers, mainly the USA, but also France, Germany, Ireland, Japan, Russia, Spain & Switzerland (in descending order of readership numbers). We even have reader(s) in Cambodia!
I've got interesting ideas for possible developments in 2013 for this Blog, including;
1) Re-design, and migrate the site over to WordPress at some point, to make it a proper website, instead of a Blog & add useful new features.
2) Expand the site to include guest writers, so that we can extend the coverage & make reports more frequent, with it no longer relying on me doing everything (although in order to pay guest writers, I might have to consider introducing a modest subscription).
3) I want to spend more time in the City, meeting company managements, and doing more in-depth company analysis & reports here. This rather hinges on point 2 above though.
So, bearing in mind that's it's been a good year for small caps generally, how have my main stock picks here fared? Pretty well actually!
Let the figures do the talking! 63% average gain over 8 stocks - RESULT!!!
What is even more remarkable, is that this is over 6 months, not even a year!
OK, I got lucky with the timing, and I also got lucky with some great stock picks (!!!). But also I only bought things that were cheap.
Here is a table of all my main articles here this year, and the average % gain (excludes dividends, but also excludes bid/offer spread & dealing costs);

Here is a review of my "main write-ups" articles here from this year.

Shortly afterwards, on 21 June I reviewed results from Norcros (NXR) and saw good upside. They were 11p then, they are 13.25p now, a 20% increase, plus they pay a decent divi. Although the quoted Bid/Offer spread can be particularly bad with NXR, so essential to get inside the spread using a proper telephone broker.
Norcros is a SETSmm stock, so a good broker can work a buy order for you at the BID price (and when you want to exit, work a sell order at the Offer price).
I cannot emphasise enough that getting a proper telephone broker is absolutely essential with small caps (if you are typically dealing in trades of say £3k+), the savings can be spectacular.
For example today the market spread on NXR was 12.75p Bid, 13.75p Offer. I rang my broker to see what prices are available, and the RSP machines (the things that discount online brokers use for small trades) were offering small amounts of stock at 13.4p, a useful saving. However, my telephone broker is able to go on the Bid on the SETS order book, at 12.75p with a Buy order. Or he could leapfrog the existing buyer sitting on the Bid at 12.75p, and put in a Buy order at 13p, which is fairly likely to be filled, if you're patient (it might take a couple of days).
So a buy at 13p would save 5.4% from the quoted market price, and if I got lucky and was filled at 12.75p, then that would save me 7.3% on the quoted market spread!
So paying 0.5% commission (or even less) to a proper telephone broker is a complete no-brainer compared with the false economy of a discount online broker (which are better suited to liquid stocks, and small transactions).
One of my ideas for 2013 is that myself & an investing friend are trying to build a group of investors with my broker, so that we can act together on certain stocks, e.g. to pool our orders and take out a line of cheap Institutional stock, to participate in Placings, to cross stock between ourselves at the mid-price, etc, and generally create an internal market to benefit us all (e.g. if one of us wants to sell some NXR, but another member of our group wants to buy, then we'll arrange the deal between ourselves & our mutual broker will just cross the stock at the mid-price). There is only room for 20-30 people in this group, as I don't want to get bogged down.
If you tend to invest in similar stocks to myself, and this might be of interest to you, then please feel free to contact me through paulypilot AT gmail DOT com to discuss further. I'm thinking in particular here of people I already know through Motley Fool, etc. But like-minded newcomers would be considered too.
My big success story of 2012 has of course been Trinity Mirror (TNI), where my in-depth analysis here has proved bang on the money, when the shares were just 25p.
They are now 92p, so a spectacular 268% rise from when I wrote about them, although as mentioned at the time, I sold my shares at 64p when the phone-hacking scandal seemed to be kicking off again.

I'm kicking myself for having sold out too soon, although I remain of the view that the phone-hacking issue moved up a gear this year, and is now a potentially dangerous & unquantified liability that is not on the balance sheet.
Combined with the declining nature of newspapers, the debt, and pension deficit (minus the freehold property), then in my opinion a share price just shy of 100p is probably about right, even though it's still only a PER of under 4.
There could be more speculative upside, and often these things become momentum plays, but for me the easy, safe money has been made, so it's no longer of interest to me at 92p. There might be a chance to revisit TNI more cheaply in June 2013, when the phone hacking cases are expected to come to Court. So I suspect it's not the last that we'll hear of that story, and of course there might be political pressure to crucify Piers Morgan (I do hope so!), in order to take the heat off Andy Coulson. It could get messy again for TNI, so I feel safe being out of the shares, with the profit banked.
My in-depth analysis of Home Retail Group (HOME) also proved correct, with 3 detailed articles (I also went to Milton Keynes for their AGM) published here between 19 June to 4 July. I remember spending 3 hours on the beach at Hove, going through their Annual Report with a fine toothcomb!
The shares were 83p then, they are 126p now, a rise of 52%. Although as with TNI, personally I sold too early at 105p (my Achilles Heel unfortunately, too quick to hit the sell button).

Whilst it looks fully valued to me for the moment, at 126p, it should be said that HOME is a vastly safer retail recovery play than Dixons Retail, in my opinion, due to the ultra-strong balance sheet at HOME, and the ropey one at Dixons. So if anyone is likely to be last man standing, it's HOME rather than Dixons. I think a pairs trade (long HOME at 126p and short DXNS at 28p) would be a very interesting side bet, taking a long-term (2 years+) view.
As always, these are just opinions, and some will be right, and some wrong. So as usual, please always do your own research.
On 5 July (and again in Dec) I met the management of Begbies Traynor (BEG), the market's only Listed insolvency practitioner. It was 30p when I wrote about it here in July, and is 35p now, plus is paying a stonking 7% dividend yield, so that one's another pleasing work in progress.
I remain bullish on BEG, and think the shares have good upside once the chickens finally come home to roost for the many thousands of zombie companies that need restructuring through an Administration process, but which is being deferred by Banks and Govt policies. In the meantime it churns out a big dividend whilst business is slow.
On 14 July I had a speculative flutter with Snoozebox (ZZZ), love the ticker!, but got bored with that one, and became increasingly uneasy with the lofty rating for a start-up that has not yet turned in a profit. Although the shares are still 58p, 10% up on the price I mentioned them here. This was not a main pick, so is not in my table below.
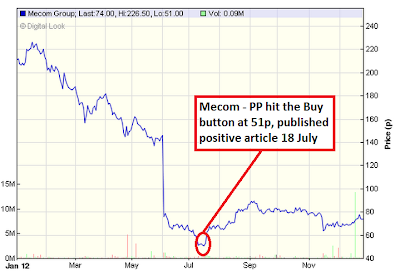
18 July saw me catch the exact bottom with Mecom (MEC), for a rapid profit, at 51p. It seemed a similar situation to TNI, so thought I would have a bit of the action here too. Although on publication of their next set of results, I was not so sure, banked the profits and moved on. I do not plan to revisit Mecom.
This is beginning to sound a bit boastful, but please allow me this indulgence, as I've had a lousy couple of years, off the boil completely, but 2012 seemed the year I finally refocussed & got my act together.
A lot of it is emotional actually. It took me a good 4 years to recover emotionally from the devastating blows that the credit crunch dealt me.
Anyway, I've got my confidence back, and instead of flailing around looking for a strategy to get back my lost millions quickly, I've refocussed on a value/growth strategy that made the money in the first place, but without the high risk of excessive gearing & huge positions in illiquid stocks (which is what killed me in 2007-8).
For readers who don't know me, I lost pretty much everything (over £6m) in 2007-8, and am rebuilding - with some very valuable lessons under my belt, learned the hard way.
Also I've learned some really great life lessons - that money isn't everything (it helps, but no more than that, once you're beyond basic needs), and that the treadmill of earning more, paying more tax, seeking incrementally better material possessions, repeat until dead - is ridiculous & pointless.
Also, that the self-importance & selfishness that rapid & considerable financial success tends to create, can often isolate you from the people who really matter - your friends & family. Or rather, the pursuit of material things just leads you to distance yourself from the people you love. Although in my own defence, I was very generous in the good times, and shared my success with everyone around me - I've never been tight, and there are a lot of happy memories from good things achieved in the good times, pre-crash.
OK just 2 more stocks to go, before this introspective gets too nauseating!
On 4 Sep I reported positively on a meeting with Directors of Staffline (STAF) at 226p. Nothing much happened for a while, but the shares have shot up recently. I've banked some profits around 300p, as top-slicing gainers is always a good strategy & frees up cash for the next big idea.
I still really like STAF, and remain a shareholder, but would like to see more up-to-date figures before increasing my position again. The Govt welfare to work programmes are good, but may consume a considerable amount of working capital in the short term.

Finally, on 10 Oct I reported on May Gurney (MAYG) at 138p, with a very low PER and high divi yield (a typical PP value share), and am pleased to say it has risen to 180p since.
I cannot see why a price of under 250p (10 times EPS) should not be achieved in the medium term, so I remain a holder. DYOR as usual.

Little did I know, when starting this Blog in June 2012 that it would prove popular - with over 151,000 pageviews to date! On average there are around 1,200 readers per day, which is growing steadily.
Whilst that's good, and enough to make it worthwhile me writing here, surely that must only be the tip of the iceberg of people interested in small caps? So hopefully word will spread in 2013 a bit wider? I make a tiny income (£50-100 a month) from the Google ads, so thank you to people who have taken an interest.
Please bear in mind that my morning reports are published at variable times, but I always announce them via a Tweet. So follow me on Twitter @paulypilot to get notifications of every post here on your timeline. If you don't use Twitter, then you're missing out - it's an excellent tool for investors, if you take the time to use it properly & customise it to your needs.
I suspect that a lot of private investors/traders focus on the resources sector (which I don't cover at all here), since there have been rich rewards in that sector for quite a few years now, although that seemed to flip around in 2012, with conventional smaller caps generating an excellent year - e.g. the FTSE Small Caps Index is up a whopping 24.3% in 2012.
Therefore, whilst many small cap investors think that they have out-performed the market in 2012, actually most haven't, because they have erroneously compared their performance with the FTSE 100, or the AIM Index (which has been weighed down by under-performing resource sector shares).
So a big thank you to everyone who has taken an interest in my Blog this year, and also a hat tip to my overseas readers, mainly the USA, but also France, Germany, Ireland, Japan, Russia, Spain & Switzerland (in descending order of readership numbers). We even have reader(s) in Cambodia!
I've got interesting ideas for possible developments in 2013 for this Blog, including;
1) Re-design, and migrate the site over to WordPress at some point, to make it a proper website, instead of a Blog & add useful new features.
2) Expand the site to include guest writers, so that we can extend the coverage & make reports more frequent, with it no longer relying on me doing everything (although in order to pay guest writers, I might have to consider introducing a modest subscription).
3) I want to spend more time in the City, meeting company managements, and doing more in-depth company analysis & reports here. This rather hinges on point 2 above though.
So, bearing in mind that's it's been a good year for small caps generally, how have my main stock picks here fared? Pretty well actually!
Let the figures do the talking! 63% average gain over 8 stocks - RESULT!!!
What is even more remarkable, is that this is over 6 months, not even a year!
OK, I got lucky with the timing, and I also got lucky with some great stock picks (!!!). But also I only bought things that were cheap.
Here is a table of all my main articles here this year, and the average % gain (excludes dividends, but also excludes bid/offer spread & dealing costs);

Here is a review of my "main write-ups" articles here from this year.
On 18 June I wrote about Quintain Estates (QED), with the shares at 38p, after attending a meeting with management. My conclusion was that the shares had good upside potential, targeting 60p. It proved to be a well-timed trade, although I more recently went cool on the shares, and banked the profits.
I am neutral on QED at the moment, because the NAV keeps going down, and it's difficult to see how shareholder value will be outed, unless there is a takeover. It's beginning to look rather too much like a company that exists mainly for the benefit of its staff and Directors, rather than its shareholders (similar to quite a few other property companies, e.g. Inland).

Shortly afterwards, on 21 June I reviewed results from Norcros (NXR) and saw good upside. They were 11p then, they are 13.25p now, a 20% increase, plus they pay a decent divi. Although the quoted Bid/Offer spread can be particularly bad with NXR, so essential to get inside the spread using a proper telephone broker.
Norcros is a SETSmm stock, so a good broker can work a buy order for you at the BID price (and when you want to exit, work a sell order at the Offer price).
I cannot emphasise enough that getting a proper telephone broker is absolutely essential with small caps (if you are typically dealing in trades of say £3k+), the savings can be spectacular.
For example today the market spread on NXR was 12.75p Bid, 13.75p Offer. I rang my broker to see what prices are available, and the RSP machines (the things that discount online brokers use for small trades) were offering small amounts of stock at 13.4p, a useful saving. However, my telephone broker is able to go on the Bid on the SETS order book, at 12.75p with a Buy order. Or he could leapfrog the existing buyer sitting on the Bid at 12.75p, and put in a Buy order at 13p, which is fairly likely to be filled, if you're patient (it might take a couple of days).
So a buy at 13p would save 5.4% from the quoted market price, and if I got lucky and was filled at 12.75p, then that would save me 7.3% on the quoted market spread!
So paying 0.5% commission (or even less) to a proper telephone broker is a complete no-brainer compared with the false economy of a discount online broker (which are better suited to liquid stocks, and small transactions).
If you would like a recommendation/introduction to my broker, then let me know, as I have a special deal on commissions & service. This is restricted to investors who trade in reasonable size/frequency (trading at least 3 times per month, and whose typical trade size is at/above £5-10k).
One of my ideas for 2013 is that myself & an investing friend are trying to build a group of investors with my broker, so that we can act together on certain stocks, e.g. to pool our orders and take out a line of cheap Institutional stock, to participate in Placings, to cross stock between ourselves at the mid-price, etc, and generally create an internal market to benefit us all (e.g. if one of us wants to sell some NXR, but another member of our group wants to buy, then we'll arrange the deal between ourselves & our mutual broker will just cross the stock at the mid-price). There is only room for 20-30 people in this group, as I don't want to get bogged down.
If you tend to invest in similar stocks to myself, and this might be of interest to you, then please feel free to contact me through paulypilot AT gmail DOT com to discuss further. I'm thinking in particular here of people I already know through Motley Fool, etc. But like-minded newcomers would be considered too.
My big success story of 2012 has of course been Trinity Mirror (TNI), where my in-depth analysis here has proved bang on the money, when the shares were just 25p.
They are now 92p, so a spectacular 268% rise from when I wrote about them, although as mentioned at the time, I sold my shares at 64p when the phone-hacking scandal seemed to be kicking off again.

I'm kicking myself for having sold out too soon, although I remain of the view that the phone-hacking issue moved up a gear this year, and is now a potentially dangerous & unquantified liability that is not on the balance sheet.
Combined with the declining nature of newspapers, the debt, and pension deficit (minus the freehold property), then in my opinion a share price just shy of 100p is probably about right, even though it's still only a PER of under 4.
There could be more speculative upside, and often these things become momentum plays, but for me the easy, safe money has been made, so it's no longer of interest to me at 92p. There might be a chance to revisit TNI more cheaply in June 2013, when the phone hacking cases are expected to come to Court. So I suspect it's not the last that we'll hear of that story, and of course there might be political pressure to crucify Piers Morgan (I do hope so!), in order to take the heat off Andy Coulson. It could get messy again for TNI, so I feel safe being out of the shares, with the profit banked.
My in-depth analysis of Home Retail Group (HOME) also proved correct, with 3 detailed articles (I also went to Milton Keynes for their AGM) published here between 19 June to 4 July. I remember spending 3 hours on the beach at Hove, going through their Annual Report with a fine toothcomb!
The shares were 83p then, they are 126p now, a rise of 52%. Although as with TNI, personally I sold too early at 105p (my Achilles Heel unfortunately, too quick to hit the sell button).

Whilst it looks fully valued to me for the moment, at 126p, it should be said that HOME is a vastly safer retail recovery play than Dixons Retail, in my opinion, due to the ultra-strong balance sheet at HOME, and the ropey one at Dixons. So if anyone is likely to be last man standing, it's HOME rather than Dixons. I think a pairs trade (long HOME at 126p and short DXNS at 28p) would be a very interesting side bet, taking a long-term (2 years+) view.
As always, these are just opinions, and some will be right, and some wrong. So as usual, please always do your own research.
On 5 July (and again in Dec) I met the management of Begbies Traynor (BEG), the market's only Listed insolvency practitioner. It was 30p when I wrote about it here in July, and is 35p now, plus is paying a stonking 7% dividend yield, so that one's another pleasing work in progress.
I remain bullish on BEG, and think the shares have good upside once the chickens finally come home to roost for the many thousands of zombie companies that need restructuring through an Administration process, but which is being deferred by Banks and Govt policies. In the meantime it churns out a big dividend whilst business is slow.
On 14 July I had a speculative flutter with Snoozebox (ZZZ), love the ticker!, but got bored with that one, and became increasingly uneasy with the lofty rating for a start-up that has not yet turned in a profit. Although the shares are still 58p, 10% up on the price I mentioned them here. This was not a main pick, so is not in my table below.
18 July saw me catch the exact bottom with Mecom (MEC), for a rapid profit, at 51p. It seemed a similar situation to TNI, so thought I would have a bit of the action here too. Although on publication of their next set of results, I was not so sure, banked the profits and moved on. I do not plan to revisit Mecom.

This is beginning to sound a bit boastful, but please allow me this indulgence, as I've had a lousy couple of years, off the boil completely, but 2012 seemed the year I finally refocussed & got my act together.
A lot of it is emotional actually. It took me a good 4 years to recover emotionally from the devastating blows that the credit crunch dealt me.
Anyway, I've got my confidence back, and instead of flailing around looking for a strategy to get back my lost millions quickly, I've refocussed on a value/growth strategy that made the money in the first place, but without the high risk of excessive gearing & huge positions in illiquid stocks (which is what killed me in 2007-8).
For readers who don't know me, I lost pretty much everything (over £6m) in 2007-8, and am rebuilding - with some very valuable lessons under my belt, learned the hard way.
Also I've learned some really great life lessons - that money isn't everything (it helps, but no more than that, once you're beyond basic needs), and that the treadmill of earning more, paying more tax, seeking incrementally better material possessions, repeat until dead - is ridiculous & pointless.
Also, that the self-importance & selfishness that rapid & considerable financial success tends to create, can often isolate you from the people who really matter - your friends & family. Or rather, the pursuit of material things just leads you to distance yourself from the people you love. Although in my own defence, I was very generous in the good times, and shared my success with everyone around me - I've never been tight, and there are a lot of happy memories from good things achieved in the good times, pre-crash.
OK just 2 more stocks to go, before this introspective gets too nauseating!
On 4 Sep I reported positively on a meeting with Directors of Staffline (STAF) at 226p. Nothing much happened for a while, but the shares have shot up recently. I've banked some profits around 300p, as top-slicing gainers is always a good strategy & frees up cash for the next big idea.
I still really like STAF, and remain a shareholder, but would like to see more up-to-date figures before increasing my position again. The Govt welfare to work programmes are good, but may consume a considerable amount of working capital in the short term.

Finally, on 10 Oct I reported on May Gurney (MAYG) at 138p, with a very low PER and high divi yield (a typical PP value share), and am pleased to say it has risen to 180p since.
I cannot see why a price of under 250p (10 times EPS) should not be achieved in the medium term, so I remain a holder. DYOR as usual.

I am sorry this sounds like a brag-fest, but it's been a cracking year, and the results above are ALL the results from the main write-ups here, not a carefully selected list of edited highlights (with losers quietly ignored).
I cannot guarantee any results for 2013, it's all unknown, but for the moment am enjoying basking in the results from a cracking inaugural year here.
But I'll do my best to keep trawling the markets for you on an (almost) daily basis, and above all ANALYSING company results. There are plenty of free & paid-for sites where you can get news, but there aren't many places to get proper analysis from people who understand business, and have run companies themselves.
Hopefully that is the point of difference here, something that I intend building on in 2013.
So, what about my favourite shares for 2013?
No contest, its Vianet (VNET) at 101p, and IndigoVision (IND) at 367p.
Why? Vianet is a cracking growth story, about to unfold, which is paying a 5.5% dividend before the growth takes off. And a fwd PER as low as 6. Negligible debt. Sound mgt. I'm very keen. Once the overhang from New Solera is cleared, it should start moving up.
IndigoVision - yes I know that it's been a long haul, but I met the new CEO (former FD, Marcus Kneen) a couple of months ago, and it's difficult to think of a more focussed & ambitious CEO, making lots of very positive changes. If IND are going to make their big breakthrough, 2013-14 will be the time.
Also, our sister site (set up & run by me), www.SmallCapValue.co.uk will be up & running again shortly - unfortunately there was an IT disaster on Boxing Day, and my hosting company have not yet restored the backup.
It's a perfect companion site to this one, as it focuses on a proven stock filtering method, based on Performance Analysis Scores, developed over 30 years by leading UK academics. It's only been soft-launched so far, as I've got problems with IP, licences, etc, but hope to resolve them soon & do a big launch in 2013.
There are other projects in the pipeline too, so a busy year ahead!
Above all, I hope you & your loved ones are all happy and healthy in 2013 - that's what really matters. If we all make a few quid too, then that's a bonus.
Best Wishes for 2013,
Paul.
Tuesday, December 18, 2012
Tue 18 Dec - UNG, DLC, IPEL, QPP
Several interesting small cap RNSs today. Universe Group (UNG) is a £7.5m (at 4p/share) payment and loyalty systems group. It's hovered on my radar for years, and management impressed at a FinnCap/Mello Central event earlier this year.
Their pre-close trading update today looks good - profits will be ahead of market expectations. They are also confident about the outlook for 2013. I have an indirect shareholding in Universe, through Vianet (VNET), which holds 13.2m shares (7%) in Universe. The hideous bid/offer spread puts me off, although a good telephone broker can usually solve that problem by ringing round the various market makers to find shares priced well within the spread.
Anyone interested in a broker recommendation is welcome to email me privately, as I have a special arrangement with a proper broker which is priced very competitively, but only available to investors who trade in reasonable size/frequency (say £10k+ deals, several per month).
CAD/CAM software group, Delcam (DLC) continues its excellent performance, with a trading statement indicating profits will be ahead of current market expectations of £4.3m. Sales have reached a new high of £46m for the year.
Very good to see Delcam actually state what market expectations are, which few companies do. So often one is left scrabbling around trying to find out what figure a company thinks it is likely to beat! So let's hope more companies adopt this very helpful approach of specifying the market expectations figure which you are expecting to beat. It's surprising how often market expectations vary from one informational website to another.
On a PER of 17, and with a yield of just under 1%, Delcam doesn't exactly look a bargain, but high quality companies rarely do.
Specialist publisher of car repair manuals, Haynes (HYNS) puts out a trading update with somewhat mixed messages, but seems to overall be saying that conditions remain tough. This is another company which is struggling to find a direction to take in the move to digital. Although one would imagine that car repair manuals are one area where sticking with a hard-backed paper product makes a lot more sense than trying to go digital - I rebuilt a MkI Vauxhall Cavalier in my student days using a Haynes manual, and the idea of fiddling with an iPad whilst loosening bolts underneath the chassis, covered from head to toe in oil & grit, just doesn't make sense!
Beware of the published mkt cap with Haynes - I seem to recall that it has 2 types of shares in issue, so the apparently cheap £11.3m mkt cap shown on some websites is incorrect! The PER is about 10, which doesn't appeal to me, I'd want an entry price of half that for a company with an uncertain strategy & future.
A share which looks potentially interesting is recruitment company Impellam (IPEL). Their trading statement this morning confused me, as I mis-read it as saying that operating profit is going to be £3m lower at £5.5m. But if you look closer, it's actually saying that exceptional charges are going to be £5.5m, and that operating profit will be £3m lower than last year.
So I now have to look up what last year's profit was, which was around £24m, so it seems to be saying that profit this year should be £21m. Could they not have simply said so in the first place?! So Delcam wins this morning's clear RNS award, and Impellam gets the most confusing RNS of the day award. Please just keep it simple - we have to read so many of these things, clarity is everything.
They are proposing a £15m special dividend, which together with a PER which looks low, makes this one an interesting potential buy. Sadly the ludicrous bid/offer spread of 305p/325p rules it out - absolutely crazy for a £140m mkt cap company.
Yet buys seems to be going through at 317p, a full 8p within the quoted spread! Market Makers - why do you keep doing this?! i.e. publishing a ridiculously wide spread, then actually transacting at much tighter prices? Since most private investors use online brokers, not telephone brokers, this just puts people off from dealing at all. So the liquidity dries up, so you then make the quoted spread even wider still!
We all want to see more liquidity in smaller caps, and that will only happen if the Market Makers tighten the quoted spread to the minimum level they are prepared to transact at. Not an artificially wide spread which seems to be set wide, in order to deter anyone from dealing at all! Just quote the price we can actually deal at! Jesus, it's not rocket science, is it?!!!
Quindell Portfolio (QPP) puts out another positive trading update. I don't like this company one bit, it reminds me too much of all those dodgy car hire companies that never got paid by the insurance companies (Helphire, Accident Exchange, etc) - reporting bigger & bigger profits, and longer & longer debtors, until eventually it all implodes. Quindell may be completely different, but it set off alarm bells when I looked at it a while back, and it usually pays to listen to your instincts. I lost a lot of money on Accident Exchange, hence am not going anywhere near anything in an even vaguely similar area ever again.
Their pre-close trading update today looks good - profits will be ahead of market expectations. They are also confident about the outlook for 2013. I have an indirect shareholding in Universe, through Vianet (VNET), which holds 13.2m shares (7%) in Universe. The hideous bid/offer spread puts me off, although a good telephone broker can usually solve that problem by ringing round the various market makers to find shares priced well within the spread.
Anyone interested in a broker recommendation is welcome to email me privately, as I have a special arrangement with a proper broker which is priced very competitively, but only available to investors who trade in reasonable size/frequency (say £10k+ deals, several per month).
CAD/CAM software group, Delcam (DLC) continues its excellent performance, with a trading statement indicating profits will be ahead of current market expectations of £4.3m. Sales have reached a new high of £46m for the year.
Very good to see Delcam actually state what market expectations are, which few companies do. So often one is left scrabbling around trying to find out what figure a company thinks it is likely to beat! So let's hope more companies adopt this very helpful approach of specifying the market expectations figure which you are expecting to beat. It's surprising how often market expectations vary from one informational website to another.
On a PER of 17, and with a yield of just under 1%, Delcam doesn't exactly look a bargain, but high quality companies rarely do.
Specialist publisher of car repair manuals, Haynes (HYNS) puts out a trading update with somewhat mixed messages, but seems to overall be saying that conditions remain tough. This is another company which is struggling to find a direction to take in the move to digital. Although one would imagine that car repair manuals are one area where sticking with a hard-backed paper product makes a lot more sense than trying to go digital - I rebuilt a MkI Vauxhall Cavalier in my student days using a Haynes manual, and the idea of fiddling with an iPad whilst loosening bolts underneath the chassis, covered from head to toe in oil & grit, just doesn't make sense!
Beware of the published mkt cap with Haynes - I seem to recall that it has 2 types of shares in issue, so the apparently cheap £11.3m mkt cap shown on some websites is incorrect! The PER is about 10, which doesn't appeal to me, I'd want an entry price of half that for a company with an uncertain strategy & future.
A share which looks potentially interesting is recruitment company Impellam (IPEL). Their trading statement this morning confused me, as I mis-read it as saying that operating profit is going to be £3m lower at £5.5m. But if you look closer, it's actually saying that exceptional charges are going to be £5.5m, and that operating profit will be £3m lower than last year.
So I now have to look up what last year's profit was, which was around £24m, so it seems to be saying that profit this year should be £21m. Could they not have simply said so in the first place?! So Delcam wins this morning's clear RNS award, and Impellam gets the most confusing RNS of the day award. Please just keep it simple - we have to read so many of these things, clarity is everything.
They are proposing a £15m special dividend, which together with a PER which looks low, makes this one an interesting potential buy. Sadly the ludicrous bid/offer spread of 305p/325p rules it out - absolutely crazy for a £140m mkt cap company.
Yet buys seems to be going through at 317p, a full 8p within the quoted spread! Market Makers - why do you keep doing this?! i.e. publishing a ridiculously wide spread, then actually transacting at much tighter prices? Since most private investors use online brokers, not telephone brokers, this just puts people off from dealing at all. So the liquidity dries up, so you then make the quoted spread even wider still!
We all want to see more liquidity in smaller caps, and that will only happen if the Market Makers tighten the quoted spread to the minimum level they are prepared to transact at. Not an artificially wide spread which seems to be set wide, in order to deter anyone from dealing at all! Just quote the price we can actually deal at! Jesus, it's not rocket science, is it?!!!
Quindell Portfolio (QPP) puts out another positive trading update. I don't like this company one bit, it reminds me too much of all those dodgy car hire companies that never got paid by the insurance companies (Helphire, Accident Exchange, etc) - reporting bigger & bigger profits, and longer & longer debtors, until eventually it all implodes. Quindell may be completely different, but it set off alarm bells when I looked at it a while back, and it usually pays to listen to your instincts. I lost a lot of money on Accident Exchange, hence am not going anywhere near anything in an even vaguely similar area ever again.
Subscribe to:
Posts (Atom)